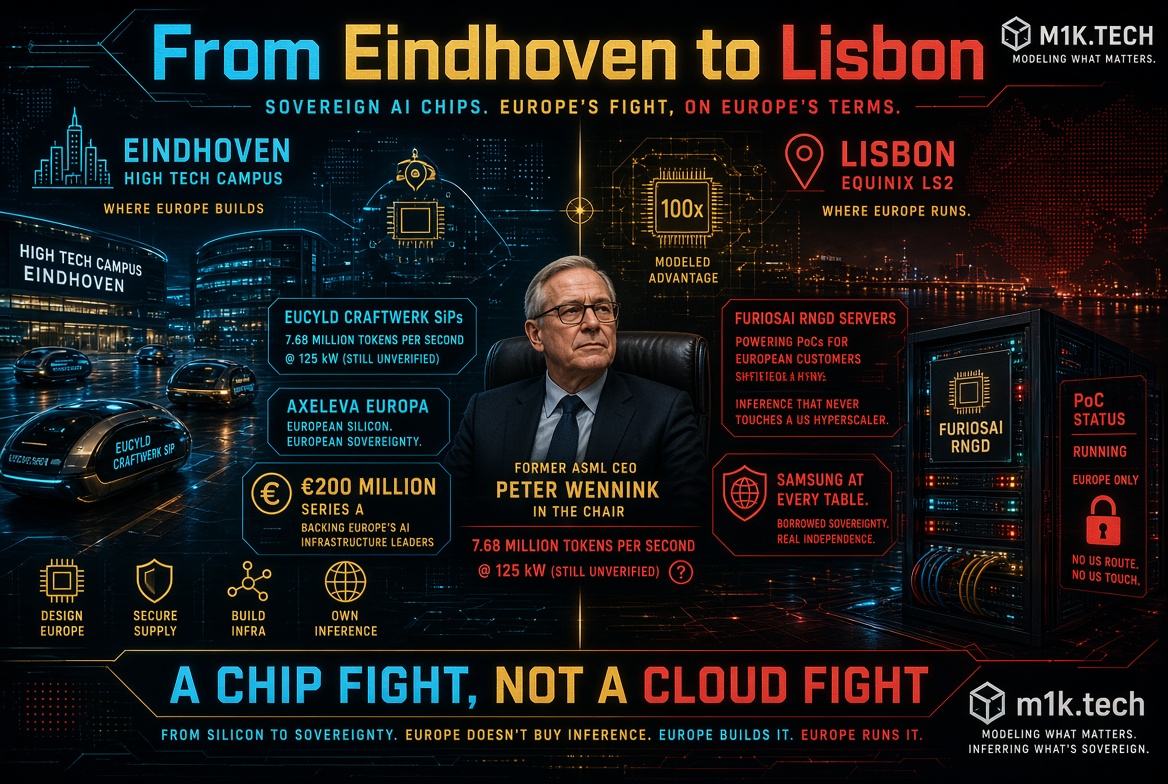
Seven point six eight million tokens per second at 125 kilowatts is the number Euclyd has been waving around for its sovereign AI chips since last November, and on Tuesday the Eindhoven startup got more than €200 million in Series A money to find out whether it’s real, with former ASML CEO Peter Wennink taking the non-executive chair. The same day in Seoul, Equinix Korea stood up at a media briefing next to FuriosaAI and explained why the Korean chipmaker’s RNGD servers are sitting in a Lisbon data center, running proof-of-concept trials with European customers who want inference that doesn’t touch a US hyperscaler.
I wrote on past Monday that Europe’s sovereign AI argument has mostly been a cloud-contract argument, a fight over which region your data lands in and who holds the keys. This week it started looking like a silicon argument, and chips are where I actually feel at home, so I have opinions.
One correction to the way this is being passed around. Furiosa didn’t switch on Lisbon this week. The RNGD deployment at Equinix’s LS2 facility was announced back in early July, timed to the RAISE Summit in Paris. What’s new is the progress report: Furiosa has had its second-generation RNGD cards and servers in mass production since January, the Lisbon machines are now running PoCs with local customers, and both companies told reporters they’re going after Europe first because GDPR and the AI Act create demand for locally run sovereign compute, before expanding to the Americas and Southeast Asia. It’s Furiosa’s first commercial footprint in Europe. That’s the milestone, and it’s a slower-burning one than the headline suggests.
Euclyd is the one that made me sit up. The company is barely two years old, founded in 2024 by Bernardo Kastrup and Atul Sinha on the High Tech Campus in Eindhoven, and the architecture pitch is aggressive. Craftwerk, which Euclyd markets as “agentic AI silicon,” is a system-in-package that pairs programmable ASIC compute with a custom memory design Euclyd calls Ultra Bandwidth Memory, stacked with 2.5D/3D packaging. Thirty-two of those SiPs go into one CWS 32 rack, which Euclyd says delivers 1.024 exaflops of FP4 compute and 32 TB of that memory. The throughput claim, 7.68 million tokens per second in multi-user mode at 125 kW, is modeled on Llama 4 Maverick, and it’s where the “100x better power efficiency and cost per token” line comes from.
I want to be careful with that number, because I’ve watched too many startup decks lean on precision games. An exaflop at FP4 isn’t the same unit of work as an exaflop at FP8 or FP16, and quoting compute at the lowest precision you support is how you get the biggest figure on the slide. The part I find more convincing is the diagnosis. Inference on large models is memory-bandwidth bound long before it’s compute bound; you spend most of your watts shuffling weights and KV cache between memory and logic. Euclid’s whole design philosophy- processor and memory designed together instead of an accelerator bolted to whatever HBM supply the market allows- attacks the right bottleneck. A 125 kW rack also lands in the same power envelope as a liquid-cooled Nvidia rack-scale system, which tells me they’re pitching a like-for-like swap in a hall that’s already provisioned, not an exotic deployment. Whether a modeled 100x survives contact with real tokenizers, real batch mixes, and real software stacks is the entire question, and nobody outside Euclyd has validated it at scale yet. I also haven’t seen Euclyd say publicly where Craftwerk gets fabbed, which matters a lot for anything calling itself sovereign.
Furiosa sits at the opposite end of the ambition curve, and that’s its strength. RNGD is built on TSMC’s 5nm process around Furiosa’s Tensor Contraction Processor architecture, with HBM from SK hynix, 512 teraflops of FP8 compute and a 180 W thermal design per card. Eight cards fit in a server that tops out around 3 kW, air-cooled, standard rack. For comparison, a DGX-class Nvidia box runs well past 10 kW and increasingly wants liquid cooling. Furiosa won’t win a raw throughput fight with Blackwell and doesn’t pretend to. The pitch is that a mid-sized European enterprise with a colocation cage and no appetite for a cooling retrofit can run a 100B-plus open-weight model on hardware it can buy outside the US. The software story is further along than I expected: PyTorch models go through Furiosa’s compiler, ONNX imports work, there’s an OpenAI-compatible API, and the company says it has validated production inference on gpt-oss 120B, LG’s Exaone 236B and Qwen 3-30B-A3B. Its third-generation part, co-developed with Broadcom, moves to HBM4 and targets trillion-parameter models, which puts it back in the memory-supply fight everyone else is losing.
Neither company is alone, and the timing on Tuesday is almost comic. Axelera AI, also based in Eindhoven, launched its second-generation Europa chip the same day, said it has signed AI-factory supply contracts worth “tens of millions,” and claimed more than 600 customers plus a $1.5 billion pipeline that its own CEO stressed isn’t orders or revenue. Europa slots into specified Dell and Supermicro systems, which is the kind of boring OEM qualification that actually moves units. Axelera has raised more than $450 million since 2021, including a $250 million-plus round in February led by Innovation Industries, the same fund that co-led Euclyd. Two inference chip companies a short bike ride apart, sharing a lead investor, both announcing on the same Tuesday. Eindhoven is having a moment.
Add France’s VSORA, Britain’s Fractile and Spain’s Semidynamics to the field, and you get the uncomfortable picture: Europe now has more inference silicon startups than it has obvious anchor customers. Look at how the EuroHPC AI factories are actually specified. Italy’s €290 million IT4LIA build runs on Nvidia Grace and Blackwell for the main system, with a separate inference partition using Axelera accelerators and SiPearl processors. Germany’s HammerHAI follows a similar mix. That’s the realistic shape of “sovereign” compute for the next few years: a European sidecar bolted onto an American core, and it’s the same pattern I flagged when EuroHPC’s newest supercomputer went to Bull and skipped Nvidia while the demand math still didn’t add up.
Globally, the inference-chip market is where every Nvidia challenger has retreated to, because training lock-in is brutal and inference is where the power bill lives. Nvidia itself is the benchmark everyone quotes, and Euclyd pointedly benchmarks against Vera Rubin. In the US the specialist field is crowded with well-funded names, and the hyperscalers keep pulling more of their inference onto in-house silicon, which squeezes the merchant opportunity from the top. Even model labs are doing it; I wrote about Anthropic building its own custom silicon team only last month. For a European startup, the realistic customer isn’t a hyperscaler; it’s the sovereign buyer, the regulated enterprise, and the AI factory with an EU procurement mandate. That’s a real market. It’s also a smaller one than the decks imply.
The corporate thread I keep pulling on is Samsung. Samsung co-led Euclyd’s round. Samsung’s Catalyst Fund is in Axelera. And last week Samsung wrote the biggest check in Mistral’s record €3 billion round. Three deals in a few months reads like a plan to me: Samsung is buying a seat at every table where European AI sovereignty gets built, and every one of those tables eventually needs memory, and maybe foundry capacity. Meanwhile, Furiosa, the other Korean company in this story, builds on TSMC and SK hynix. Europe’s “sovereign” AI stack is increasingly a Korean-supplied one, which is fine by me; Korea isn’t the geopolitical risk anyone in Brussels is losing sleep over, but it’s worth saying out loud. Equinix is the quiet winner on the infrastructure side; being the neutral colo where buyers can test non-Nvidia hardware without committing a hall is a nice business to be in.
Wennink’s move matters more than a board seat usually does. He ran ASML for a decade and knows exactly how long it takes to turn a physics bet into something a fab will buy. He’d already backed Euclyd as an investor last year; taking the chair is a louder statement, and a useful one when you’re recruiting chip architects who could walk into Nvidia or Apple instead. The establishment signal is real. It doesn’t validate the 100x.
The financing mix is the most European thing about all of this. Euclyd’s round was co-led by Samsung, Somerset Capital Partners, the EQT-managed Scaleup Europe Fund and Innovation Industries, with Denmark’s EIFO, imec.xpand, the Brabant development agency BOM and Quadri joining. The Scaleup Europe Fund was built to write €100 million to €500 million checks into deep tech, exactly the band where European startups used to have to fly to California. That gap is closing, and I’m glad. What still worries me is the next round. A €200 million Series A funds tape-out and a few racks; it doesn’t fund volume production, a software ecosystem and a global sales team at the same time, and a Series B in the billion range is where European capital has historically run out. Furiosa’s own path is instructive. It has raised more than $250 million and was reportedly shopping a $300 million to $500 million round ahead of a planned IPO. After watching Pasqal list on Nasdaq and come up short of its target, I’m not convinced public markets will be generous to the next pre-revenue European hardware name either.
So is this a turning point? Partly. Europe finally has money, a credible chairman, and working hardware in a Lisbon rack, which is more than it had a year ago. But sovereignty that runs on Korean memory, Taiwanese wafers, and a CUDA-shaped software world is still borrowed sovereignty. The first European inference chip that ships in real volume into a real AI factory, with benchmarks someone else ran, gets my full attention. Euclyd has the most to prove and the loudest number, and I’d love to be wrong about how hard that 100x will be to keep.
Sources
- Techzine, Eindhoven-based EUCLYD raises 200 million for more energy-efficient AI chips, September 15, 2026
- EUCLYD via PR Newswire, EUCLYD Raises Over €200 Million to Break the AI Efficiency Wall, September 15, 2026
- Euclyd, Euclyd Unveils CRAFTWERK
- Seoul Economic Daily, Equinix, FuriosaAI Team Up to Target Europe’s Sovereign AI Demand, September 15, 2026
- DCD, FuriosaAI deploys its RNGD servers at Equinix data center in Lisbon, Portugal
- The Next Web, FuriosaAI brings its Nvidia-rival chips to Europe
- Reuters via Global Banking & Finance, European chip startup Axelera wins AI factory supply deals, September 15, 2026
- Tech.eu, Dutch AI inference chipmaker Axelera AI raises $250M, February 24, 2026
- The Deep Dive, AI Chip Startup Targets $1.5 Billion Deals, Lands Dell, Supermicro Integrations